You may not think about central banks when paying a mortgage, using a credit card, investing in stocks, or checking the value of the U.S. dollar. Yet decisions made by these institutions influence borrowing costs, inflation, employment conditions, bond yields, currencies, and financial markets around the world.
For Americans, the most familiar example is the Federal Reserve, or Fed. The Federal Reserve is the central bank of the United States. Its responsibilities include monetary policy, financial stability, supervision of financial institutions, payment-system operations, and consumer and community-related functions. Its monetary policy mandate includes maximum employment and stable prices.
Other major institutions include the European Central Bank, Bank of Japan, Bank of England, Bank of Canada, Swiss National Bank, and Reserve Bank of Australia.
Although their specific mandates differ, these institutions share a common objective: maintaining a monetary and financial environment in which an economy can function effectively.
Understanding what they do can help investors make better sense of changes in interest rates, currencies, bonds, stocks, commodities, and economic conditions.
What Are Central Banks?
A central bank is a public institution responsible for important parts of a country’s or currency area’s monetary and financial system.
Unlike an ordinary commercial bank, it does not primarily exist to offer checking accounts, mortgages, or credit cards to consumers.
Instead, its responsibilities can include:
- Setting monetary policy
- Influencing interest rates
- Promoting price stability
- Supporting financial-system stability
- Providing liquidity during financial stress
- Managing or supporting payment systems
- Issuing currency
- Managing foreign-exchange reserves
- Supervising financial institutions in some jurisdictions
- Serving as banker or fiscal agent to the government
Not every central bank performs every function.
For example, the Bank of Canada notes that it handles monetary policy, financial-system stability, currency, funds management, and regulatory oversight of certain financial-market infrastructures, while other Canadian regulators supervise individual banks.
That is why investors should understand each institution’s actual mandate instead of assuming all central banks work in exactly the same way.
Why Do Central Banks Matter?
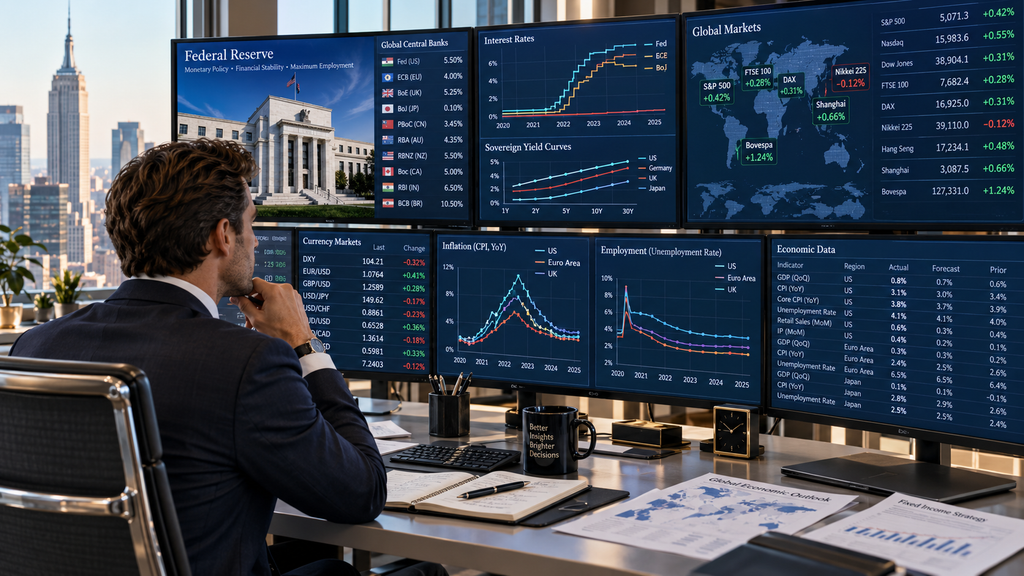
Modern economies depend heavily on credit.
Households borrow to purchase homes and cars. Businesses borrow to expand operations. Governments issue bonds. Banks lend money to consumers and companies.
The cost and availability of that credit affect economic activity.
By influencing financial conditions, central banks can encourage or restrain borrowing, spending, and investment.
Their decisions can eventually affect:
- Mortgage rates
- Business loans
- Savings yields
- Credit conditions
- Employment
- Inflation
- Currency values
- Bond prices
- Stock-market valuations
The Federal Reserve explains that changes in short-term policy conditions can influence longer-term interest rates, foreign-exchange rates, money and credit, employment, output, and prices.
This does not mean a central bank directly controls every interest rate or market price. Instead, monetary policy works through a chain of financial and economic relationships.
The Main Goals of Central Banks
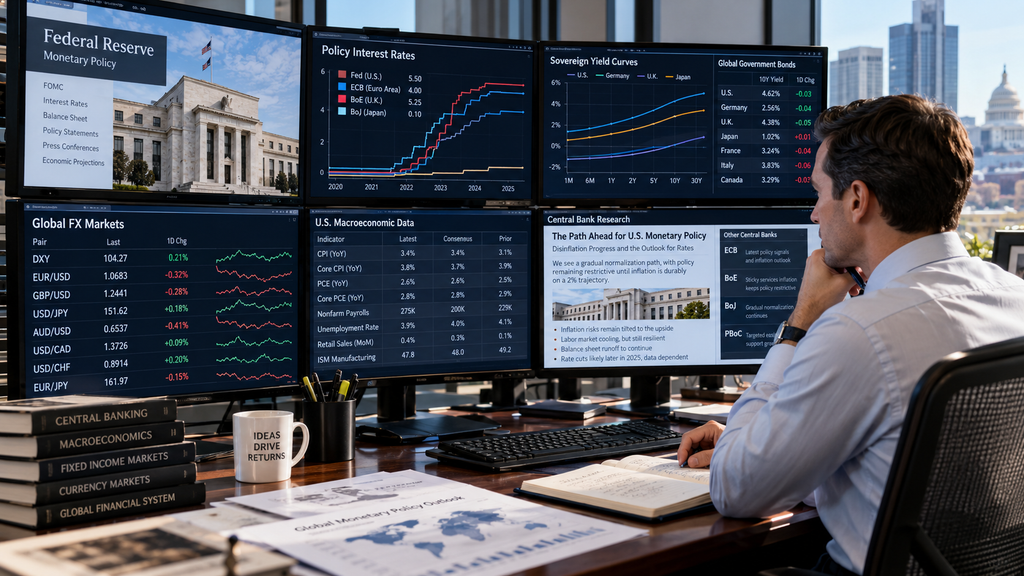
Different institutions operate under different laws, but several goals appear repeatedly.
Price Stability
Inflation is one of the most important concerns of monetary policy.
If prices rise too quickly for too long, purchasing power falls and economic planning becomes more difficult for households and businesses.
Central banks therefore often aim to keep inflation low and reasonably stable.
The European Central Bank states that its primary objective is maintaining price stability in the euro area.
The Bank of Japan also identifies price stability as the objective of its monetary policy.
Employment and Economic Activity
Some central banks also have explicit employment objectives.
The Federal Reserve’s monetary policy mandate includes maximum employment and stable prices.
Australia’s Reserve Bank similarly conducts monetary policy with objectives that include price stability and full employment.
Central banks generally do not try to maximize economic growth at any cost. Rapid growth accompanied by persistent inflation or financial instability can create new problems.
The challenge is balancing competing risks.
Financial Stability
Central banks also monitor the health of the broader financial system.
Financial instability can occur when banks, markets, or payment systems stop functioning normally.
During severe stress, a central bank may provide liquidity so that short-term funding problems do not spread throughout the system.
The Bank of Canada, for example, describes itself as an ultimate source of liquidity and lender of last resort for Canada’s financial system.
How Central Banks Use Interest Rates
Interest rates are the monetary policy tool that receives the most public attention.
When policymakers want to reduce inflationary pressure, they may tighten monetary conditions.
When economic activity is weak and inflation is sufficiently controlled, they may ease policy.
Why Higher Rates Can Slow an Economy
Higher interest rates can make borrowing more expensive.
That can affect:
- Mortgages
- Auto financing
- Business loans
- Corporate debt
- Credit cards
- Real-estate development
As borrowing becomes more expensive, households and businesses may reduce spending or delay investment.
Lower demand can eventually reduce inflation pressure.
Why Lower Rates Can Support Activity
Lower interest rates can reduce borrowing costs and encourage spending or investment.
Businesses may find expansion projects more attractive, while households may face more favorable financing conditions.
However, rate cuts are not automatically positive for financial markets.
If a central bank lowers rates because economic conditions are deteriorating rapidly, investors may focus more on the underlying weakness than on cheaper financing.
Context matters.
Quantitative Easing and Central Bank Balance Sheets
Interest rates are not the only monetary policy tool.
During periods of severe financial stress or exceptionally weak economic conditions, some central banks have used large-scale asset purchases, often called quantitative easing or QE.
A central bank may purchase government bonds or other eligible securities.
These purchases can affect longer-term yields, market liquidity, and broader financial conditions.
The opposite process is commonly called quantitative tightening, or QT, when balance-sheet holdings decline.
For investors, balance-sheet policy matters because it can influence bond markets and liquidity conditions even when the policy interest rate remains unchanged.
Forward Guidance: Why Central Bank Words Move Markets
Markets react not only to what policymakers do today but also to what investors believe they may do tomorrow.
That is why policy statements, press conferences, meeting minutes, and economic projections receive so much attention.
Central-bank communication can influence expectations about:
- Future interest rates
- Inflation
- Economic growth
- Balance-sheet policy
- Financial risks
This practice is often called forward guidance.
ZitaPlus’s overview of major central banks similarly emphasizes that markets frequently move on expectations before an actual policy change takes place.
For investors, this means a rate decision cannot always be interpreted by looking only at whether the bank raised, lowered, or held rates.
The explanation may matter just as much.
Major Central Banks Investors Follow
Several institutions receive particularly close attention because of the size of their economies and financial markets.
The Federal Reserve
The Federal Reserve is the central bank most directly relevant to U.S. households and investors.
It conducts monetary policy, supports financial stability, supervises certain financial institutions, and plays an important role in U.S. payment and settlement systems.
Changes in U.S. monetary conditions can influence Treasury yields, corporate borrowing, mortgages, the dollar, and global financial markets.
European Central Bank
The European Central Bank manages monetary policy for the euro area.
Its primary goal is price stability, and the Eurosystem also conducts foreign-exchange operations, manages foreign reserves, and promotes the smooth operation of payment systems. The ECB also has banking-supervision responsibilities.
Because the euro is one of the world’s major currencies, ECB policy is watched closely by global investors.
Bank of Japan
The Bank of Japan is responsible for monetary policy in Japan and states that its objective is maintaining price stability.
It uses money-market operations and other tools to influence interest rates and monetary conditions.
Japan’s large bond market and the yen’s role in global finance make Bank of Japan decisions important well beyond Japan.
Bank of England
The Bank of England is the United Kingdom’s central bank.
Its responsibilities include monetary stability and financial stability.
The Bank’s Monetary Policy Committee sets monetary policy with the goal of achieving the U.K.’s inflation objective, while other parts of the institution help protect financial-system stability.
Bank of Canada
The Bank of Canada focuses on monetary policy, financial stability, currency, government funds management, and oversight of important payment and financial-market systems.
Its monetary framework aims to keep inflation low, stable, and predictable.
Swiss National Bank
The Swiss National Bank conducts monetary policy for Switzerland.
Its legal mandate requires it to ensure price stability while taking economic developments into account.
The Swiss franc’s international role means SNB decisions can receive significant attention in currency markets.
Reserve Bank of Australia
The Reserve Bank of Australia conducts monetary policy, supports financial stability, issues banknotes, operates important settlement services, and manages foreign-exchange and gold reserves.
Its monetary framework places emphasis on price stability and full employment.
How Central Banks Affect the Stock Market
Interest-rate expectations influence stock valuations because investors compare the expected returns of stocks with returns available from bonds and cash.
Higher yields can make safer fixed-income assets more competitive.
They can also increase financing costs for companies.
Growth companies can be especially sensitive because much of their valuation may depend on profits expected far into the future.
However, the relationship is not automatic.
Stocks can rise during periods of high rates if corporate earnings remain strong, and they can fall after rate cuts if investors are concerned about recession.
Investors should therefore look at monetary policy together with economic growth, earnings, inflation, and financial conditions.
How Central Banks Affect Bonds
Bond markets often react directly to changes in monetary-policy expectations.
When investors expect higher rates, existing bonds with lower yields may become less attractive, which can pressure their prices.
When expected rates fall, bond prices can benefit.
Shorter-term government bonds tend to be particularly sensitive to expectations about near-term policy, while longer-term yields also reflect inflation expectations, growth expectations, and other risks.
How Central Banks Affect the U.S. Dollar
Currency values are strongly influenced by differences in interest rates and economic expectations across countries.
Suppose investors expect U.S. interest rates to remain higher than rates in another major economy.
All else being equal, dollar-denominated assets may become relatively more attractive.
However, exchange rates also depend on:
- Economic growth
- Inflation
- Trade flows
- Political and financial risks
- Investor sentiment
- Capital flows
This is why currency markets pay close attention to differences, or divergence, between major central-bank policies.
Central Banks and Gold
Gold does not pay interest, so changes in interest rates and inflation-adjusted yields can influence its relative appeal.
When real yields are high, income-producing assets may look more attractive compared with gold.
When real yields fall, gold can become relatively more appealing to some investors.
The dollar also matters because gold is commonly priced in U.S. dollars.
However, gold prices can also respond to geopolitical risk, central-bank reserve purchases, inflation concerns, and broader investor sentiment.
No single central-bank variable determines its price.
Central Bank Independence
Many major central banks are designed to have a significant degree of operational independence from day-to-day political decision-making.
The purpose is to allow monetary policy to focus on legislated economic objectives rather than short-term political preferences.
Independence does not mean a central bank is free from accountability.
Major institutions regularly publish policy decisions, reports, meeting information, speeches, forecasts, and other explanations of their actions.
The Bank of Japan, for example, explicitly identifies both independence and public accountability as elements of its monetary-policy framework.
What Investors Should Watch
You do not need to predict every interest-rate decision to understand central-bank policy.
Instead, monitor several broader signals:
Inflation Data
Persistent inflation can influence how long tighter policy remains necessary.
Employment Data
Labor-market conditions can affect decisions where employment forms part of the central bank’s mandate.
Economic Growth
Weakening activity may create pressure for easier monetary conditions.
Policy Statements
Small changes in language can reveal how policymakers’ thinking is evolving.
Balance-Sheet Policy
Asset purchases or reductions can influence financial conditions beyond the headline policy rate.
Differences Between Countries
Policy divergence can influence exchange rates and international capital flows.
Frequently Asked Questions
What are central banks?
Central banks are public institutions responsible for functions such as monetary policy, financial stability, currency issuance, payment systems, and, in some countries, banking supervision.
What is the central bank of the United States?
The Federal Reserve System is the central bank of the United States. It was created under the Federal Reserve Act of 1913.
Why do central banks raise interest rates?
They may tighten monetary policy when inflationary pressure is too strong. Higher borrowing costs can reduce demand and help bring inflation toward the institution’s objective.
Why do central banks cut interest rates?
Rate cuts can ease financial conditions when economic activity is weak and inflation conditions allow it. The effect depends on the broader economic environment.
Do central banks control mortgage rates?
Not directly. Their policy decisions influence short-term rates and broader financial conditions, which can eventually affect mortgage rates and other borrowing costs.
What is quantitative easing?
Quantitative easing generally refers to large-scale asset purchases by a central bank intended to influence longer-term interest rates, liquidity, and broader financial conditions.
What is the difference between the Fed and the ECB?
The Fed conducts monetary policy for the United States and has a mandate that includes maximum employment and stable prices. The ECB conducts monetary policy for the euro area, with price stability as its primary objective.
Why do investors follow central banks?
Central-bank decisions can affect interest rates, bond yields, currency values, credit conditions, stock valuations, and overall economic activity.
Conclusion
Central banks sit at the center of the modern financial system.
Their responsibilities extend far beyond simply raising or cutting interest rates. Depending on the institution, they can manage monetary policy, support financial stability, oversee payment systems, provide emergency liquidity, manage reserves, issue currency, and supervise parts of the banking system.
For U.S. investors, the Federal Reserve receives the most attention because its policies directly influence American financial conditions. But global markets are interconnected, which means decisions by the European Central Bank, Bank of Japan, Bank of England, Bank of Canada, Swiss National Bank, Reserve Bank of Australia, and other institutions can also matter.
The most useful approach is not to assume that every rate increase is bad for stocks or every rate cut is good.
Instead, ask why policy is changing.
Is inflation improving? Is economic growth weakening? Are financial risks increasing? Is one country following a very different monetary path from another?
Those questions provide far more context than the rate decision alone.
Understanding central banks will not tell you exactly where the market will move tomorrow, but it can help explain why borrowing costs, currencies, bonds, equities, and commodities behave the way they do.
For anyone trying to understand investing and the global economy, central-bank policy is one of the most important pieces of the puzzle.