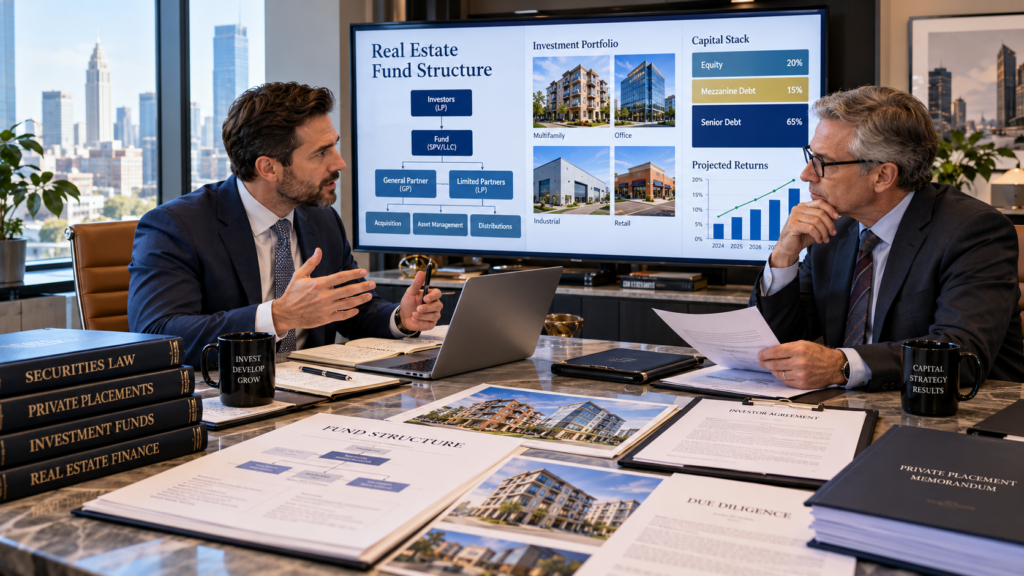
Launching a real estate investment fund involves much more than finding attractive properties and raising money from investors.
A sponsor also needs to decide how the fund will be structured, how investors will participate, what securities exemption may apply, how fees and profits will be divided, how investment decisions will be made, and what information must be disclosed before investors commit capital.
That is why working with a real estate fund formation attorney can be an important part of the process.
A fund formation attorney helps sponsors create the legal structure around a real estate investment strategy. This can include forming fund and management entities, preparing offering documents, analyzing federal and state securities laws, designing investor economics, addressing investment adviser issues, and helping manage legal requirements throughout the life of the fund.
The SEC describes a private fund as an entity that pools capital from multiple investors while relying on exclusions from registration as an investment company. Private funds commonly use exemptions such as Rule 506(b) or Rule 506(c) of Regulation D when raising capital.
Because each real estate fund can have different investors, assets, economics, and marketing plans, legal structure should usually be considered before fundraising begins rather than after capital has already been solicited.
What Does a Real Estate Fund Formation Attorney Do?
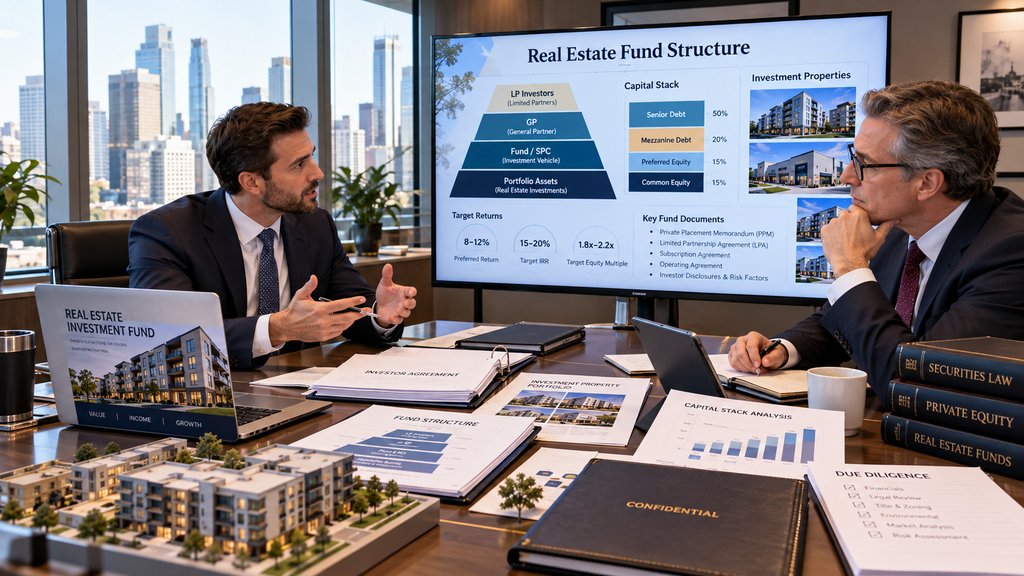
A real estate fund lawyer helps create and document the legal framework through which capital is raised, managed, invested, and eventually returned to investors.
The work often begins before the first investor is contacted.
At that stage, the attorney may discuss:
- Investment strategy
- Target fund size
- Types of real estate assets
- Investor profile
- Expected holding period
- Fund duration
- Capital contribution structure
- Management fees
- Sponsor compensation
- Profit-sharing arrangements
- Fundraising strategy
- Securities-law exemptions
The goal is to design a structure that matches how the sponsor actually intends to operate.
The Crowdfund Lawyer’s fund formation practice, for example, includes closed-end, open-end, semi-specified, blind-pool, and co-GP structures as well as fund agreements, side letters, management agreements, carried-interest structures, investor waterfalls, Investment Advisers Act counseling, Investment Company Act analysis, and ongoing governance.
Why Real Estate Funds Involve Securities Law
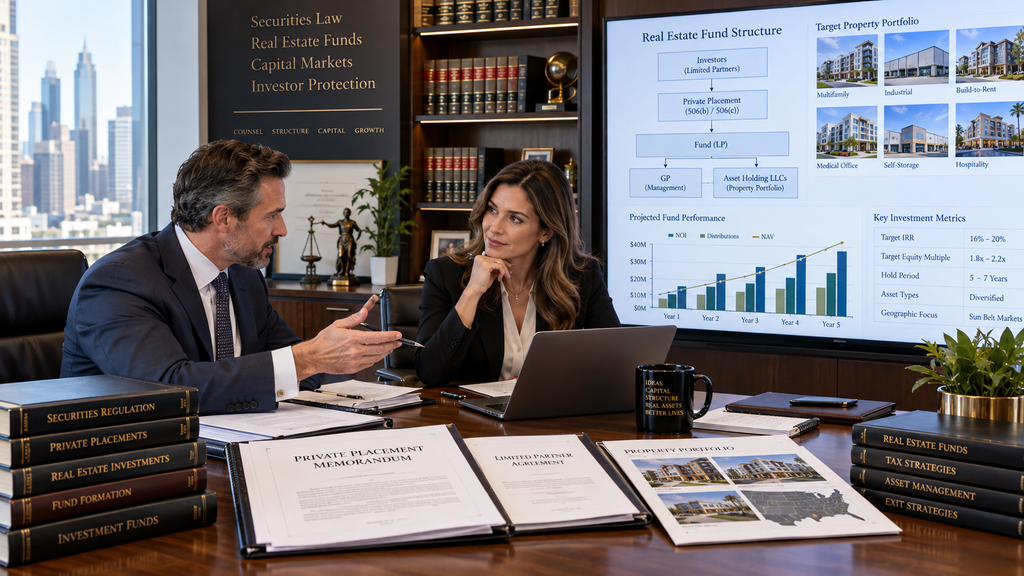
One of the most important concepts for sponsors to understand is that raising passive investor capital usually involves securities laws.
When investors contribute money to a real estate vehicle and rely primarily on the sponsor or manager to generate returns, the offering may involve securities.
That means the fund cannot simply collect money and begin investing without considering federal and state requirements.
Private Funds Usually Rely on Exemptions
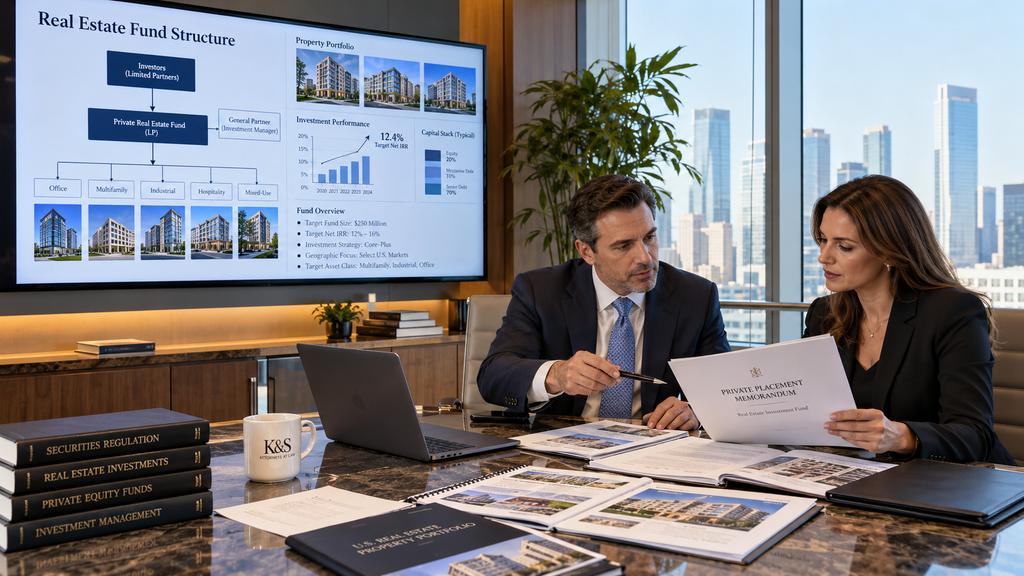
Private real estate funds commonly rely on an exemption from full SEC registration.
Two frequently used exemptions for capital raises are Rule 506(b) and Rule 506(c) of Regulation D. The SEC identifies both as common methods for private funds raising capital.
The right exemption depends on factors such as:
- Whether the sponsor plans to advertise publicly
- Whether non-accredited investors may participate
- How investors are identified
- Whether accredited investor verification is required
- Whether offshore investors will participate
A real estate fund formation attorney can help analyze which structure fits the planned fundraising strategy.
Understanding Rule 506(b)
Rule 506(b) is widely used for private offerings.
One important feature is that general solicitation is generally prohibited.
That means sponsors relying on this exemption need to be careful about publicly promoting an investment opportunity through open websites, social media advertising, mass email lists, public seminars, or similar channels.
The SEC explains that Rule 506(b) generally permits private capital raising while prohibiting general solicitation.
Depending on the offering, a limited number of sophisticated non-accredited investors may also be permitted, subject to additional requirements.
The Crowdfund Lawyer describes 506(b) as a structure often used where a sponsor has existing investor relationships and does not need public advertising.
Understanding Rule 506(c)
Rule 506(c) works differently.
This exemption can allow broad public solicitation, but participating investors must generally be accredited and the issuer must take reasonable steps to verify accredited status.
The SEC makes an important distinction between the standards used in the two exemptions. Under Rule 506(b), the issuer generally needs a reasonable belief that an investor qualifies as accredited. Under Rule 506(c), the issuer must take reasonable steps to verify accredited investor status.
This verification requirement is one reason sponsors should determine their exemption strategy before beginning marketing.
Changing strategies after public advertising has already started may create legal complications.
Fund Structure: LLC or Limited Partnership?
Private real estate funds are commonly organized as limited partnerships or limited liability companies.
The SEC notes that private funds and their management entities require legal formation and that limited partnerships commonly use a general partner with investors participating as limited partners. LLCs and other legal forms may also be used.
Limited Partnership Structure
In a typical limited partnership structure:
- The fund is organized as a limited partnership.
- Investors participate as limited partners.
- A general partner manages the fund.
- A separate management company may provide investment-management services.
This can clearly separate management control from passive investor ownership.
LLC Structure
Some funds use an LLC structure instead.
Members invest in the LLC, while a manager or managing member controls investment decisions according to the operating agreement.
The appropriate structure depends on tax, governance, liability, operational, and investor considerations.
A fund formation lawyer typically works with tax and accounting professionals where necessary to coordinate the structure.
Key Documents in Real Estate Fund Formation
One of the largest parts of fund formation is preparing documents that clearly define the rights and obligations of investors and managers.
Private Placement Memorandum
A private placement memorandum, or PPM, is commonly used as an offering disclosure document.
It may describe:
- Investment strategy
- Fund structure
- Sponsor background
- Fees
- Conflicts of interest
- Risk factors
- Distribution policies
- Investment restrictions
- Tax considerations
- Securities-law disclosures
The SEC lists a private placement memorandum as one of the documents frequently used during a private fund capital raise.
Limited Partnership or Operating Agreement
This document governs the legal relationship among the fund, its manager, and investors.
It may address:
- Capital commitments
- Capital calls
- Distributions
- Investor voting rights
- Management authority
- Removal rights
- Transfers
- Withdrawals
- Fund term
- Dissolution procedures
Subscription Agreement
The subscription agreement is the document through which an investor agrees to invest.
It commonly includes investor representations, eligibility information, securities-law acknowledgments, and commitments regarding the amount of capital being invested.
Management Agreement
Where a separate management company operates the fund, a management agreement may define its responsibilities, authority, compensation, and relationship to the fund.
Designing Fund Economics
A real estate fund formation attorney does more than draft legal documents.
Experienced fund counsel may also help the sponsor document and test the economic structure.
Preferred Return
A preferred return may give investors a defined priority before the sponsor participates in certain profits.
The calculation method needs to be clearly documented.
Sponsor Promote
The sponsor promote, sometimes referred to as carried interest, represents a portion of profits allocated to the sponsor after specified thresholds or return conditions are met.
Distribution Waterfall
A distribution waterfall defines the sequence in which cash is distributed.
For example, the structure may provide for:
- Return of investor capital
- Payment of a preferred return
- Sponsor catch-up, if applicable
- Remaining profits divided according to agreed percentages
The exact structure can vary substantially.
The Crowdfund Lawyer’s fund-formation practice specifically lists preferred returns, sponsor promotes, waterfalls, management fees, expense allocations, and LP economics as areas addressed during structuring.
Closed-End, Open-End, and Blind-Pool Funds
Not all real estate funds operate the same way.
Closed-End Fund
A closed-end real estate fund generally has a defined fundraising period, investment period, and eventual liquidation timeline.
It may acquire a portfolio of assets, hold them for several years, then sell and distribute proceeds.
Open-End Fund
An open-end fund may operate continuously and allow capital to enter over a longer period.
These structures can require more complex valuation, admission, withdrawal, and liquidity provisions.
Blind-Pool Fund
In a blind-pool fund, investors commit capital before all specific properties have been identified.
Investors are therefore placing significant trust in the sponsor’s investment strategy and judgment.
Semi-Specified Fund
A semi-specified fund may fall between a single-asset syndication and a full blind pool.
Some initial assets or a clearly defined pipeline may already exist, while additional investments are selected later.
These differences affect disclosures, governance, investor expectations, and documentation.
Real Estate Fund vs. Real Estate Syndication
Sponsors often use the terms fund and syndication interchangeably, but they commonly refer to different structures.
Single-Asset Syndication
A syndication is often formed around one known property or clearly identified deal.
Investors know what asset the capital will generally be used to acquire.
Multi-Asset Fund
A fund typically invests across multiple properties or loans according to a broader investment strategy.
The Crowdfund Lawyer describes its syndication practice as focused on single-asset raises and its fund-formation work as designed for sponsors moving toward scalable multi-asset investment vehicles.
Sponsors moving from individual deals to a fund structure may need more sophisticated governance and operational systems.
Investment Adviser Issues
Forming the fund is only one part of the legal analysis.
The entity or person managing the investments may also be considered an investment adviser.
The SEC explains that private fund advisers may need to register with the SEC or state regulators unless they qualify for an exemption. Advisers solely to private funds with less than $150 million in U.S. private-fund assets may potentially qualify for a federal private fund adviser exemption, though state requirements and other conditions must still be analyzed.
This area can become complex quickly.
A fund attorney may therefore evaluate:
- Adviser registration requirements
- Exempt reporting adviser status
- State registration rules
- Assets under management
- Management activities
- Compensation arrangements
State Securities and Blue Sky Requirements
Federal securities exemptions do not necessarily eliminate all state-level filing obligations.
Many offerings require notices or filings in states where investors reside.
The Crowdfund Lawyer lists Blue Sky and state securities compliance among the services it coordinates for real estate offerings.
Sponsors raising from investors across multiple states should identify these obligations early.
When Should You Hire a Real Estate Fund Formation Attorney?
Ideally, before you begin actively soliciting investors.
The structure of the fund and the securities exemption can influence what you are allowed to say publicly and how you can approach investors.
The Crowdfund Lawyer specifically recommends involving securities counsel before investor outreach begins, particularly because fundraising communications can affect the availability of certain exemptions.
Early legal planning can also help clarify:
- Fund structure
- Target investor type
- Advertising rules
- Economics
- Management entities
- Offering documents
- Capital calls
- Reporting obligations
- Governance
How to Choose a Real Estate Fund Formation Attorney
Look for counsel with experience in both securities law and real estate capital formation.
Useful questions include:
Have You Formed Similar Funds?
A lawyer experienced with real estate funds may better understand sponsor promotes, property-level SPVs, capital calls, refinancing, acquisition pipelines, and investor waterfalls.
Do You Handle Securities Compliance?
Fund formation should not stop at creating an LLC.
Ask whether the attorney handles Regulation D, Form D filings, state notices, investor disclosures, and adviser-related issues.
Can You Help With Fund Economics?
Good fund documents should accurately reflect how distributions, fees, expenses, and governance will work in practice.
Do You Provide Ongoing Counsel?
Funds can operate for many years.
Amendments, additional closings, capital calls, investor questions, recapitalizations, dispositions, and follow-on funds may require legal assistance later.
The Crowdfund Lawyer describes its service as extending beyond formation into capital calls, amendments, investor communications, follow-on raises, recapitalizations, and dispositions.
Frequently Asked Questions
What is a real estate fund formation attorney?
A real estate fund formation attorney is a securities and corporate lawyer who helps sponsors create investment vehicles that pool investor capital to acquire or finance real estate.
Do I need an attorney to start a real estate fund?
There is no universal rule requiring the same legal arrangement for every fund, but private real estate capital raises involve securities, entity, contract, and regulatory issues. The SEC itself recommends that prospective fund managers consider working with appropriate legal counsel.
What documents are needed for a real estate fund?
Common documents may include a private placement memorandum, LLC or limited partnership agreement, subscription agreement, management agreement, investor questionnaires, and regulatory filings.
What is the difference between Rule 506(b) and Rule 506(c)?
Rule 506(b) generally prohibits general solicitation, while Rule 506(c) permits general solicitation but requires reasonable steps to verify that participating investors are accredited.
What is Form D?
Form D is a notice filing commonly associated with offerings conducted under Regulation D. Fund counsel can help determine when and how the filing applies.
Can a real estate fund invest in multiple properties?
Yes. Multi-asset investing is one of the main reasons sponsors use fund structures rather than creating a separate syndication for every property.
Can a fund accept international investors?
Potentially, but international investors introduce additional securities, tax, regulatory, and compliance issues. Structures involving Regulation S may sometimes be considered alongside domestic exemptions.
Does The Crowdfund Lawyer handle real estate fund formation?
Yes. Its current services include real estate fund formation, syndications, joint ventures, offering documents, Regulation D matters, fund economics, Investment Advisers Act and Investment Company Act counseling, and ongoing fund governance.
Conclusion
Launching a real estate fund requires both an investment strategy and a legal structure capable of supporting it.
A real estate fund formation attorney helps connect those two sides of the business.
The attorney may assist with fund and management entities, securities exemptions, offering documents, subscription agreements, investor waterfalls, sponsor economics, adviser issues, state securities compliance, and ongoing fund governance.
For sponsors moving from single-property syndications to a multi-asset platform, these decisions become even more important.
The SEC makes clear that private funds operate within a framework involving the Securities Act, Investment Company Act, and Investment Advisers Act, with different exemptions and requirements applying depending on how the fund is structured and operated.
The Crowdfund Lawyer, led by Jason Powell of Dickinson Wright, focuses on this area of real estate capital formation and currently advises sponsors on single-asset syndications, multi-asset funds, Regulation D offerings, fund economics, ongoing governance, and tokenized real estate structures.
The most important practical step is to address legal structure before fundraising begins.
Define the investment strategy. Understand who the intended investors are. Decide whether public solicitation is part of the plan. Establish the fund economics. Then work with qualified counsel to determine how the offering should be structured and documented.
Good fund formation is not simply about producing paperwork.
It is about creating a legal and operational framework that can support investor relationships, acquisitions, distributions, compliance, and future growth throughout the life of the fund.
This article is general educational information and is not legal advice. Securities and fund-formation requirements depend on the specific facts, jurisdictions, investors, and structure involved.